
Holmen's new-construction market is one of the busiest in the La Crosse area right now. The average Holmen home value sits at $422,350, up 3.9% over the past year (Zillow), and most active new builds sit in family-focused subdivisions with city sewer and water already in the ground. The real choice for a buyer isn't just which house — it's first which subdivision, then which lot, because each neighborhood carries its own price band, lot size, and builder.
I'm Jeff Thompson, a senior loan officer at Granite Bank in nearby Onalaska (NMLS# 256028), and I work with Holmen buyers every week. This guide walks every active development I can find — price, square footage, lot availability, and neighborhoods — plus the financing math that decides whether a build actually works for your budget. That last part matters more than most buyers expect: the loan that funds a new build is different from a resale mortgage, and it starts earlier.
What does the Holmen market look like in 2026?
Holmen's home values are still climbing, though the pace has cooled from the frenzied years. The average home value in Holmen sits at $422,350, up 3.9% over the past year, and homes go to pending in about 20 days (Zillow). That tells you two things: demand is healthy enough that well-priced new builds move fast, but a 3.9% rise is far from the double-digit spikes of 2021–2022 — there's still room to negotiate on finishes and lot premiums.
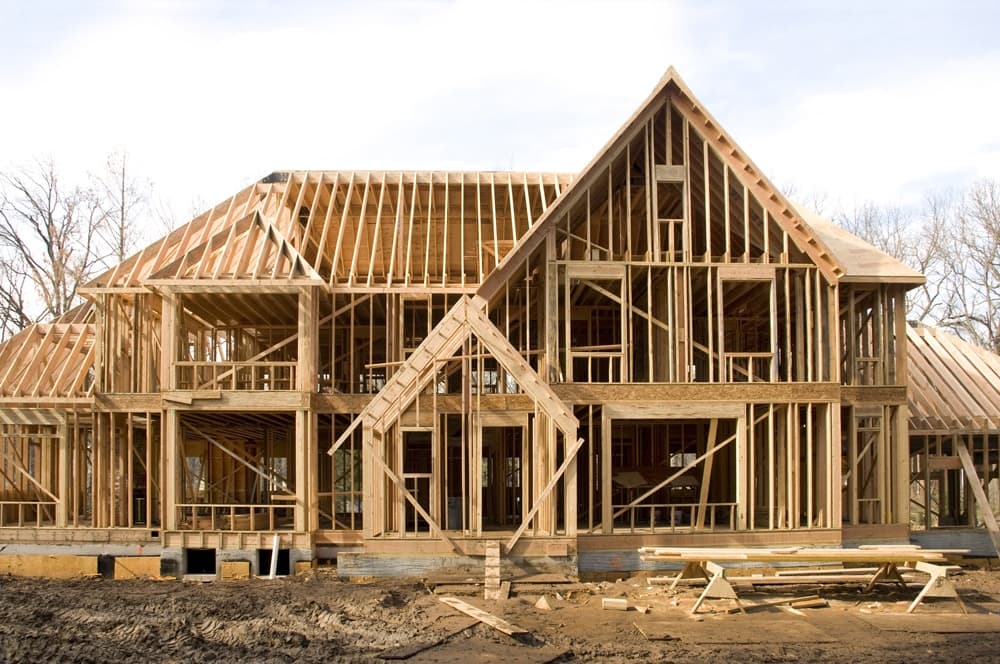
Herb & Iris Addition: the flagship new-build neighborhood
If there's one subdivision Holmen buyers ask about most, it's Herb & Iris Addition — a newer development off the south side of town where several 2026 Parade Homes have gone up. It's the kind of place where you can still customize finishes before the build finishes, which is a major draw for buyers who want new without waiting on a resale.
One active example is a new-construction ranch on Lot 3 Block 7 in Herb & Iris Addition, listed at $594,000 — about $209 per square foot across 2,829 finished square feet, with 4 bedrooms, 3 baths, and a 3-car garage on a 9,583-square-foot lot (Coldwell Banker). The listing notes that buyers can still customize nearly everything in the home — a window that closes once framing starts.
On the higher end, a 2026 Parade Home at 1413 Herb Ln is listed at $729,900 and marketed as built with gathering in mind — an open-concept main level that joins the kitchen, dining area, great room, and patio, plus a finished basement, a hidden pantry, and a tree-lined, fenced-in backyard (Instagram). It sits within walking distance of Prairie View Elementary and Holmen High School, and the listing calls it move-in ready. Compare that with the Lot 3 Block 7 ranch above: the Parade Home is the showpiece, but both sit in the same subdivision with city services already at the lot line.
Liberty Addition: build-your-own lots north of the high school
For buyers who want to pick their own lot and work with their own builder, Liberty Addition is the standout option right now. It's a brand-new residential community located just north of Holmen High School, and the developer is marketing it to both dream-home builders and investors (@properties La Crosse).
The headline number: single-family lots start at $79,900, and they're fully improved with utilities at the lot line — meaning sewer, water, and power are already brought to the edge of each lot, which saves you the time and cost of running utilities yourself. The neighborhood sits near schools, parks, the new public library, and the aquatic center, all within Holmen's school district (@properties La Crosse).
The financing angle here matters more than most buyers expect. Buying a raw lot and building on it usually requires a construction-to-permanent loan — a two-phase mortgage that pays the builder during construction, then converts to a standard home loan when you move in. That structure has different credit and down-payment requirements than a resale mortgage, and it needs to be in place before the builder starts digging, not after. The build itself is a long game: from lot purchase to move-in, most buyers should plan for a build phase of roughly 10 to 16 months on top of the 45 to 60 days it takes to close the construction loan (Amerisave).
McGilvray Park: established ranch homes with move-in-ready appeal
McGilvray Park is the subdivision buyers turn to when they want the look and feel of new construction without the construction timeline. The neighborhood features ranch-style builds with finished lower levels and three-car garages — a 2022-built ranch at 1912 McGilvray Way is listed at $499,900, with 4 bedrooms, 3 full baths, a finished lower level with a family room and bonus space, and a heated 3-car garage (Instagram).

McGilvray Park isn't strictly new construction the way Herb & Iris or Liberty Addition are — many homes here were built over the past several years and are resold within a few years of completion. That still matters for financing: a recently built home qualifies for the same first-mortgage programs as any resale, but you typically won't need a construction loan since the builder has already finished. For buyers who want to skip the build and lock in a price now, that's a real advantage over waiting a year in a construction pipeline.
How to finance your Holmen new build
No matter which subdivision you land in, the financing decision is where a new build either works or stalls. If you're buying a finished spec home or a recently built resale in McGilvray Park, a standard mortgage covers it. But if you're building — buying a Liberty Addition lot and hiring your own builder, or customizing a Herb & Iris home before framing — you need a construction-to-permanent loan: one mortgage that pays the builder in draws during construction, then converts to a fixed-rate home loan when you move in. That single-close structure avoids paying two sets of closing costs and locks your rate in one place.
The numbers matter. A conventional construction-to-permanent loan typically requires a 10% down payment and a 680 credit score (Bankrate), while an FHA-backed version drops the down payment to as little as 3.5% and the credit bar to around 580 . Many lenders quote 5% to 20% down for conventional one-time close loans depending on your credit and their guidelines (GO Mortgage). The right program hinges on your credit score, how much you can put down, and whether you already own the lot — which is exactly what I'll run with you.
This is exactly the kind of math I walk Holmen buyers through every week. I'm Jeff Thompson, Producing Sales Manager and loan officer at Granite Bank (NMLS #256028), and I've spent 24 years as a producing mortgage professional — including construction lending — out of our Onalaska office at 115 10th Ave. S., Suite 102 (Granite Bank). Whether you're pricing a lot, comparing builders, or ready to start the build, the conversation should begin before you pick a lot.
Follow my market updates and loan tips on Facebook and LinkedIn, or get in touch and we'll run your numbers.


No comments yet. Be the first to share your thoughts!