The Verdict: Why Negotiating Credits Beats Waiting for a Crash
Your 2026 Home Buying Decision Matrix
Buyer Priority | Price Reduction | Seller-Funded Credit |
|---|---|---|
Monthly Payment | Small impact (~$78 per $10k) | Massive impact ($250-$300+) |
Cash at Closing | No change | Reduces cash needed significantly |
Loan Amount | Lowers principal slightly | No change to principal |
Best For | Long-term equity building | Immediate monthly affordability |
Main Limitation | Doesn't address high rates | Capped by loan program limits |
As a Certified Mortgage Advisor in Oviedo, I see buyers daily who are sidelined by 2026's higher interest rates. The reality is that "market value" is a calculation, not just a sticker price on a Zillow listing. By shifting your focus from the asking price to the total cost of financing, you can secure a home today with a monthly budget that looks like 2021, even while prices in areas like Chuluota continue to climb (Momentum Realty).
The Math of the Buydown: Why One Number Matters More
The biggest mistake buyers make is shopping for a price rather than a payment. In our local market, the "sticker price" is often a psychological anchor that sellers are hesitant to move. However, as an Oviedo mortgage professional, I've found that sellers are frequently more open to offering interested-party contributions (IPCs) to close a deal.
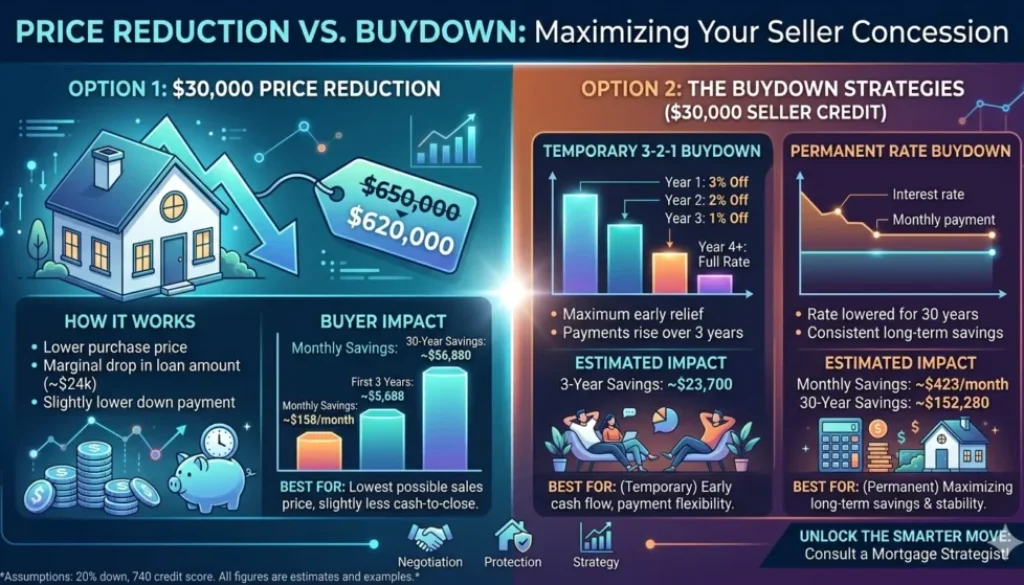
On a $450,000 30-year fixed loan at 7.24% (the Freddie Mac average as of October 2026), your principal and interest payment is approximately $3,067 (NV Real Estate Group). If you negotiate a $10,000 price drop, the savings are modest. But if you take that same $10,000 and apply it to a 2-1 Temporary Buydown, your first-year payment drops to $2,482—a savings of $585 every month. Even in the second year, you're still saving $299 monthly (NV Real Estate Group).
The Invisible Negotiables: Closing Costs and Repair Credits
Negotiation doesn't stop at the interest rate. In a "balanced" market like 32766 (Chuluota), where we currently see about 3.5 months of supply, buyers have leverage to ask for closing cost assistance that was unheard of during the 2021 frenzy (Momentum Realty).
Beyond the rate buydown, you should be looking at:
Repair Credits: Instead of asking a seller to fix an aging HVAC system, ask for a credit. This keeps the seller's cash in the deal and lets you choose your own contractor after closing.
Extended Rate Locks: If you’re buying new construction in Oviedo, negotiating for a builder-paid long-term rate lock can protect you from market volatility while the home is being completed.
Association Dues: In some Central Florida townhome communities, we are seeing savvy buyers negotiate for a year of pre-paid HOA fees, which frees up immediate monthly cash flow for furniture or move-in expenses.
Seller Psychology: Protecting the 'Comps'
Why would a seller give you $15,000 in credits but refuse to drop the price by $10,000? It comes down to neighborhood appraisals. When a home sells for a lower price, it becomes a "comp" (comparable sale) for every other home on the street, effectively lowering the value of the entire neighborhood.
Sellers and their agents are protective of that final recorded sale price. A seller credit, however, is often "invisible" in the public record. It allows the seller to net the same amount of money while maintaining the high sale price that keeps their neighbors happy and future appraisals strong. In Seminole County, where 33% of listings have already taken a price cut, sellers are looking for ways to stand out without further devaluing their property (Momentum Realty). By offering to keep the price higher in exchange for a substantial credit, you create a "win-win" that many listing agents will encourage their sellers to accept.
The Oviedo Shift: Why 2026 is a Negotiator's Market
While headlines focus on home values, the local reality in Oviedo is more nuanced. Recent data shows that the typical home in Oviedo goes under contract in approximately 24 days (Orlando Real Estate Chicks). However, a massive divide has emerged: while some homes fly off the market, over 60 out of 115 active listings (roughly 52%) have been sitting for more than 60 days.
This "stagnant" inventory is where the opportunity lies. In Oviedo, approximately 46% of recently sold homes had to reduce their asking price before finding a buyer (Orlando Real Estate Chicks). As a buyer, you aren't just competing with other buyers anymore; you are helping a seller solve a problem—specifically, a property that is costing them money every single day it sits vacant.
With 3.5 months of supply currently available in the 32766 ZIP code, the market has shifted from a seller-dominated frenzy to a balanced environment (Momentum Realty). This balance is your green light to negotiate for the rate buydowns and closing cost credits that were rarely seen just two years ago.
Navigating the 'Cap': Lender Rules for Seller Credits
One critical detail many buyers miss is that you can’t simply ask for an unlimited amount of cash from a seller. The mortgage industry has strict rules on Interested Party Contributions (IPCs). These caps are designed to prevent "artificial" price inflation, and they vary significantly depending on your loan program and down payment.
Conventional Loans: Capped at a 3% contribution if putting down less than 10% (NV Real Estate Group). On an average Oviedo home priced at $560,000 (Orlando Real Estate Chicks), this sets the ceiling for the buydowns we can negotiate.
FHA and VA Loans: Generally more generous, allowing up to a 6% seller contribution.
Investment Properties: Strictest limits, usually capping credits at 2%.
It is vital to work with a mortgage advisor before you sign a contract. If you negotiate a $20,000 credit but your loan program only allows $15,000, that extra $5,000 effectively disappears—it cannot be given back to you as cash after closing. We structure these deals to ensure every penny of the seller's contribution goes toward your bottom line, whether through a permanent rate reduction or covering your prepaid taxes and insurance.
Marriage Minute: Communication Over Criticism
In our latest Made to Be Great podcast episode, my wife and I explored how sarcasm is often just "criticism wearing a smile" (Made to be Great). After 21 years of marriage, we've learned that small jabs can slowly chip away at a couple's connection.
Buying a home is one of the most stressful events a couple can go through. It’s a time when it’s easy to let frustration turn into jabs. My challenge to you: be the person who builds your spouse up during this process. Your intentions don't erase the impact of your words—owning the effect of your communication is what builds a relationship that lasts (Made to be Great).
1What is the maximum seller credit I can receive?
Seller contribution limits vary by loan type: typically 3% for conventional loans with less than 10% down, and up to 6% for FHA and VA loans. On investment properties, the cap is usually 2%.
2Does a rate buydown affect my qualification?
For a temporary buydown (like a 2-1), you must still qualify for the mortgage based on the full note rate, not the discounted first-year rate. This ensures you can afford the home long-term.
3Is the buydown permanent?
You can choose between a temporary buydown (1-3 years of relief) or a permanent buydown (paying 'points' to lower the rate for the life of the loan). We calculate the 'break-even' point for both to see which saves you more.
Your Next Steps: Building Your Negotiation Plan
Successfully negotiating a home discount that doesn't show up on Zillow requires a coordinated effort between you, your real estate agent, and your mortgage advisor. We don't just guess at the numbers; we run the math for every specific property you're considering.
Identify Stagnant Listings: We look for homes on the market for 60+ days, as over 52% of active Oviedo listings fall into this category (Orlando Real Estate Chicks).
Run the Math: We'll provide a side-by-side comparison of a price reduction versus a permanent or temporary rate buydown.
Structure the Offer: We ensure credits are applied optimally toward non-recurring closing costs and interest rate buydowns.
The goal isn't just to get the house—it's to get the house with a financial structure that protects your family's future. If you're ready to look past the list price and find the real value in today's market, let's start that conversation.
Build Your Custom Buying Plan
Want to explore these scenarios for your specific goals? Click below to get my custom ChatGPT prompt for buyers.
Get My Strategy Prompt
No comments yet. Be the first to share your thoughts!